Twelve small challenges are easier to fit around 2027 than one huge savings target. Pick a monthly task, record the real result and change the amount when bills are heavier.
Table of contents
- 1. January: Four weekly deposits
- 2. February: A no-takeout test
- 3. March: The five-dollar Friday challenge
- 4. April: Subscription review month
- 5. May: A ten-dollar weekly transfer
- 6. June: Use-the-pantry week
- 7. July: Round-up savings
- 8. August: Back-to-school swap
- 9. September: Two-dollar daily challenge
- 10. October: Holiday sinking fund
- 11. November: A one-week no-buy category
- 12. December: The spare-change finish
- What the fixed deposits add up to
- Questions people ask
- Put January’s first deposit on the calendar
The figures below are planning examples, not a substitute for your own income and expenses. If you are behind on essential bills, deal with those first.
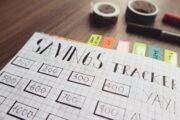
For every month, write the date and the actual amount in your tracker. A skipped purchase only counts as savings if the money stays in your account or moves to savings.
1. January: Four weekly deposits
Put aside $5 each week for a $20 total. If January bills are heavy, reduce it to $1 per week.
2. February: A no-takeout test
Choose four meals you would normally order and cook at home instead. Save only the actual price difference after grocery costs.
3. March: The five-dollar Friday challenge
Transfer $5 on each of the four Fridays in your chosen four-week period for $20. Mark dates before you start.
4. April: Subscription review month
Cancel or pause one service you no longer use. Track charges that actually stop; do not count a free trial as money saved.
5. May: A ten-dollar weekly transfer
Save $10 per week for four weeks, totaling $40. If income varies, choose four paydays or workweeks instead.
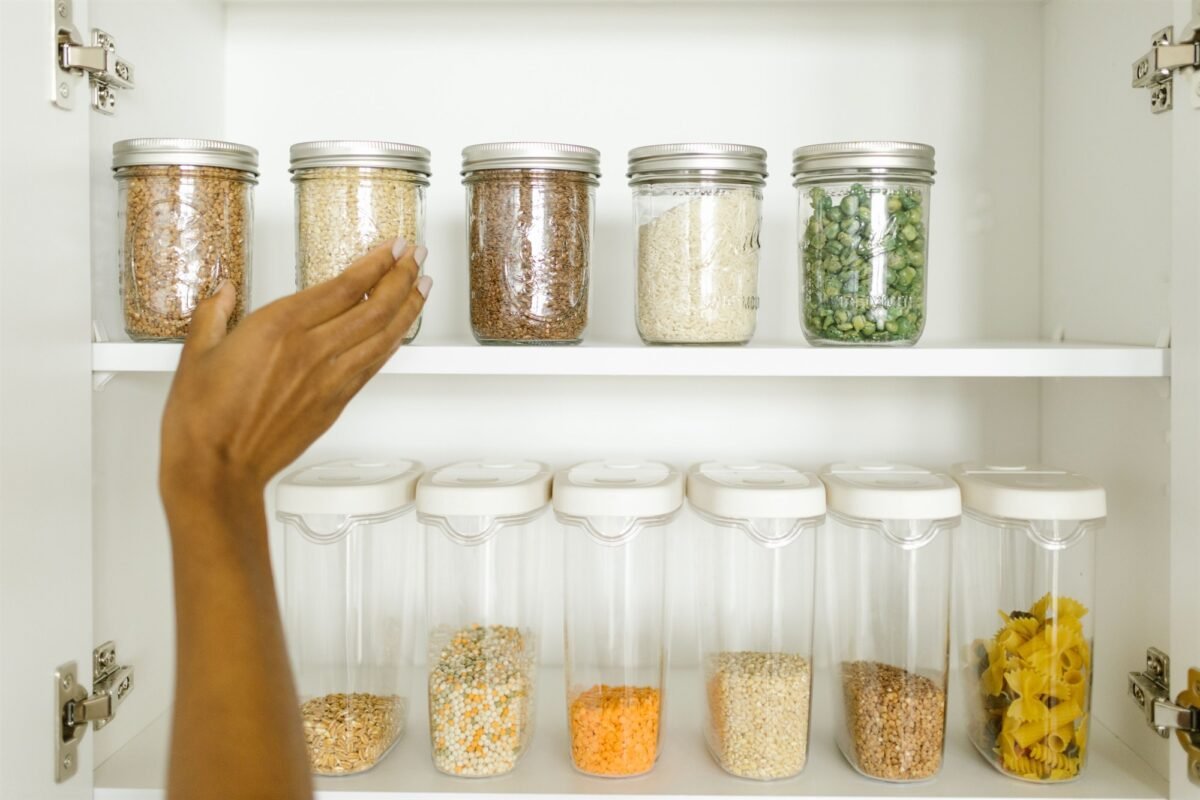
6. June: Use-the-pantry week
Plan meals around what is already in your kitchen and buy only missing ingredients. Keep grocery receipts so you can compare with a normal week.
7. July: Round-up savings
Round selected purchases up to the next dollar in a notebook and transfer the difference once a week. Set a cap so it does not interfere with bills.
8. August: Back-to-school swap
Check what can be reused, repaired or traded before buying supplies. Count only verified savings against the items you actually needed.
9. September: Two-dollar daily challenge
Set aside $2 on 15 days you choose, for $30. A missed day can be moved without doubling the next payment.
10. October: Holiday sinking fund
Save $10 each week for four weeks, totaling $40. Keep this money separate from rent and groceries.
11. November: A one-week no-buy category
Pause one nonessential category for seven days. Choose an area with spending you can actually control.
12. December: The spare-change finish
Choose five dates to transfer $4 each, totaling $20. Avoid forcing a deposit during the most expensive holiday week.
What the fixed deposits add up to
The specifically fixed-deposit months above total $170: January $20, March $20, May $40, September $30, October $40 and December $20. The other months have variable results, so there is no honest single annual savings promise.
Questions people ask
Do I have to do the challenges in this order?
No. Swap months to match your bills. If December is expensive for you, do the spare-change finish in a lighter month and use December for the one-week no-buy instead.
How much will I save in total?
The fixed-deposit months add up to $170. The no-takeout, pantry, round-up, subscription and back-to-school months depend on your own receipts, so record the real amounts rather than guessing.
Can I do two challenges in the same month?
Yes, if both fit after essentials. A subscription review pairs well with any deposit challenge because it usually takes one sitting.
Put January’s first deposit on the calendar
Choose the four dates for January’s $5 deposits now. If $5 does not fit, write $1 and start anyway.
Want a bigger goal later in the year? Try the 52-week money challenge or the 100 envelope challenge, both with free printable trackers.